On this page
Renters insurance protects your belongings and covers you if someone is hurt in your home, usually for less than $15 a month. Your landlord’s policy covers the building, not your stuff. Here are five strong renters insurance companies and how to choose the right coverage.
Disclosure: Some links may earn us a commission at no cost to you. It never affects our rankings. See our affiliate disclaimer.
Our top picks at a glance
- Best value: State Farm — the lowest average rate among highly rated insurers and local agents.
- Best digital experience: Lemonade — fast app-based quotes and claims.
- Best customer service: Amica — consistently strong service ratings.
- Best for military families: USAA — standard policies include flood and earthquake coverage.
- Best regional insurer: Erie — solid coverage and service through local agents.
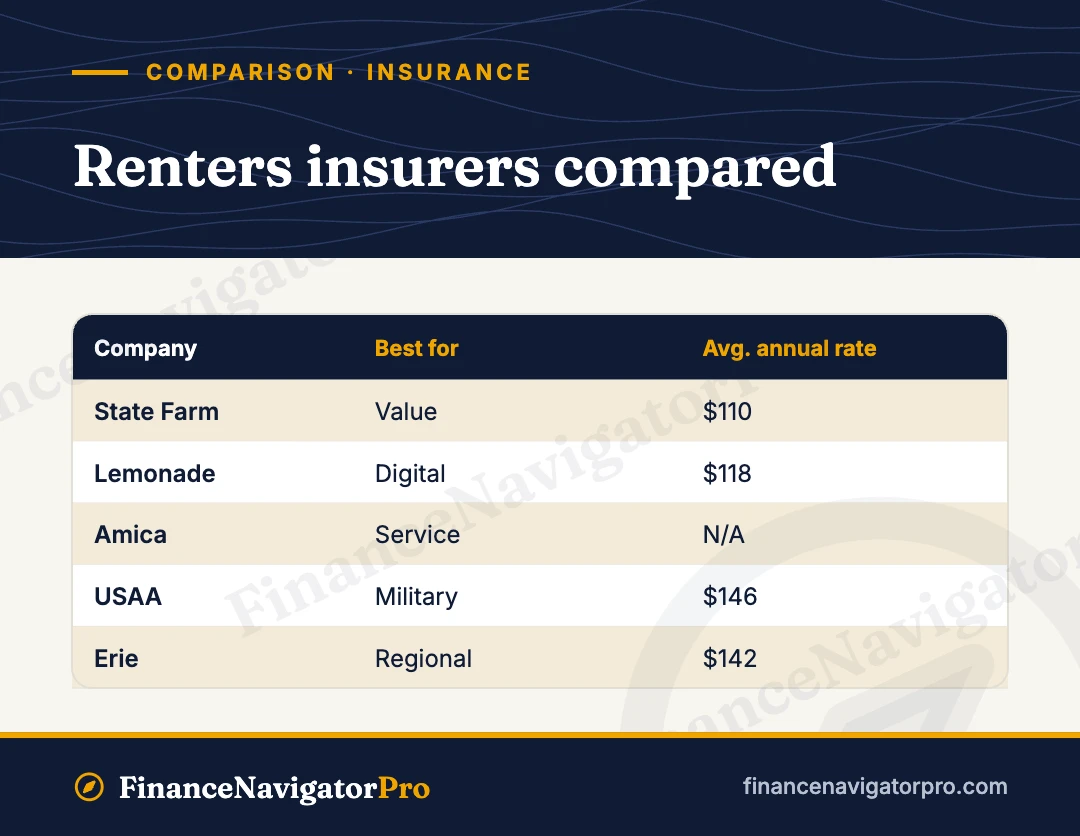
Average annual rates below come from NerdWallet’s 2026 analysis for a standard policy; your price depends on your location, coverage and deductible. Pricing and features checked November 2026; get quotes directly before you buy.
| Company | Best for | Average annual rate | How to buy |
|---|---|---|---|
| State Farm | Value | $110 | Agents, online |
| Lemonade | Digital experience | $118 | App, online |
| Amica | Customer service | Not available | Online, phone |
| USAA | Military families | $146 | Online, phone |
| Erie | Regional coverage | $142 | Local agents |
1. State Farm — Best value
State Farm, the largest U.S. home insurer, had the lowest average renters rate among NerdWallet’s top-rated companies. It sells policies nationwide through local agents and online, and bundling with auto insurance can lower your total cost.
Pros
- Low average rates
- Available nationwide with local agents
- Bundling discounts
Cons
- Fewer online-only perks than app-first insurers
- Rates vary widely by state
Who it’s for: renters who want low prices and an agent.
2. Lemonade — Best digital experience
Lemonade sells renters insurance through a fast app, with instant quotes and quick claims for simple losses. Prices are among the lowest available. It is offered in about 30 states plus Washington, D.C., and draws a high rate of complaints to state regulators.
Pros
- Quotes and claims in minutes through the app
- Low prices
- Gives part of unused premiums to charity
Cons
- Not available in every state
- High complaint rate
- No agents
Who it’s for: tech-savvy renters who want quick, low-cost coverage.
3. Amica — Best customer service
Amica consistently earns top marks for customer satisfaction and draws few complaints. It offers solid standard coverage and discounts for bundling and paying in full.
Pros
- Excellent service and low complaints
- Strong discounts
- Good digital tools
Cons
- May cost more than budget insurers
- Not the cheapest option
Who it’s for: renters who value a smooth claims experience.
4. USAA — Best for military families
USAA renters policies include coverage for flood and earthquake damage, a rare feature, plus coverage for military uniforms and equipment. It is available only to active military, veterans, some federal employees and their families.
Pros
- Flood and earthquake coverage included
- Strong customer satisfaction
- Bundling with auto and banking
Cons
- Membership restrictions
- No local agents
Who it’s for: eligible military families.
5. Erie — Best regional insurer
Erie Insurance offers solid renters coverage and good service through local agents in its operating states, mainly in the Midwest, Mid-Atlantic and Southeast.
Pros
- Solid coverage and service
- Competitive rates
- Personal service from agents
Cons
- Available in limited states
- Must buy through an agent
Who it’s for: renters in Erie’s states who prefer an agent.
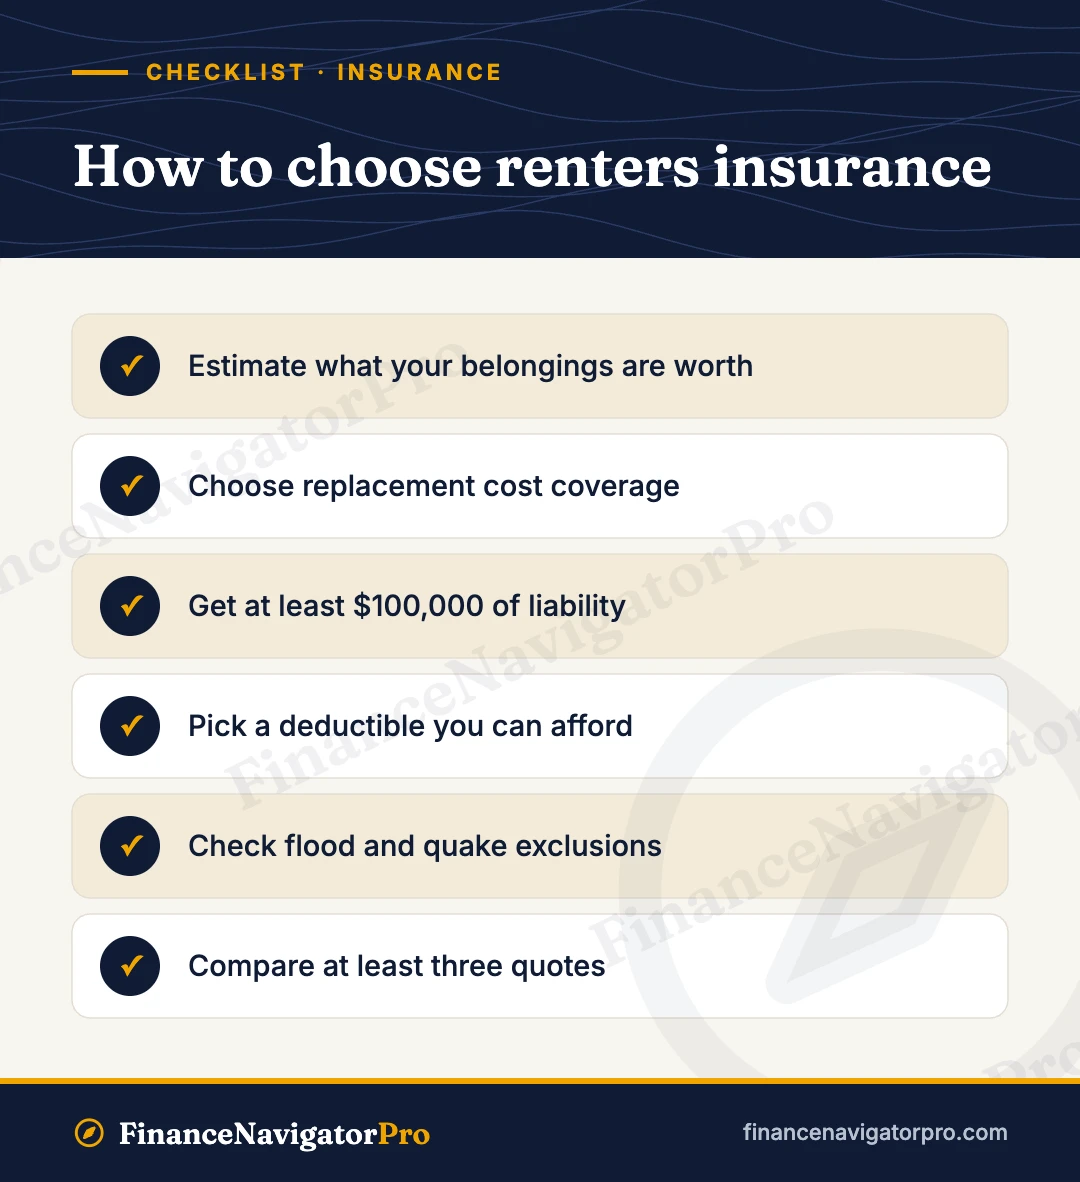
How to choose renters insurance
Estimate what your belongings are worth
Walk through your home and total up furniture, electronics, clothing and kitchen items. Most renters need $20,000 to $50,000 of personal property coverage.
Choose replacement cost coverage
Replacement cost pays to buy new items, while actual cash value subtracts depreciation. Replacement cost costs a little more but pays far more after a loss.
Get enough liability coverage
Liability coverage pays if someone is injured in your home or you damage someone else’s property. Most policies start at $100,000; $300,000 is often only a few dollars more.
Pick a deductible
A higher deductible lowers your premium. See insurance deductibles explained.
Check exclusions
Most policies exclude flood and earthquake damage. Valuable jewelry, art or collectibles may need extra coverage.
How we chose
We compared widely available renters insurers using company information, 2026 rate data and complaint records from reputable reviews. We did not accept payment for placement. We weighed price, coverage, customer satisfaction and availability.
Frequently asked questions
How much is renters insurance?
Typically about $10 to $20 a month, depending on where you live and how much coverage you choose. See how much renters insurance costs.
Is renters insurance required?
No law requires it, but many landlords require it in the lease.
Does renters insurance cover my roommate?
Usually not, unless they are named on the policy. Each roommate should generally have their own policy.
Does renters insurance cover theft outside my home?
Yes. Personal property coverage generally protects your belongings anywhere, such as a laptop stolen from your car, subject to your deductible and limits.
Bottom line
State Farm offers the best value, Lemonade the fastest digital experience, Amica the best service, USAA the broadest coverage for military families and Erie strong regional service. Choose replacement cost coverage and compare at least three quotes. Homeowner? See the best homeowners insurance companies. This article is educational and not insurance advice.
Keep reading