On this page
Buying term life insurance no longer means a nurse visit, a blood draw, and weeks of waiting. Several companies now let you apply online, answer health questions, and get a decision the same day, often with no medical exam at all. This guide is for US adults, especially parents and new homeowners, who want solid coverage from a financially strong insurer without the hassle.
Disclosure: Some links may earn us a commission at no cost to you. It never affects our rankings. See our affiliate disclaimer.
Our top picks at a glance
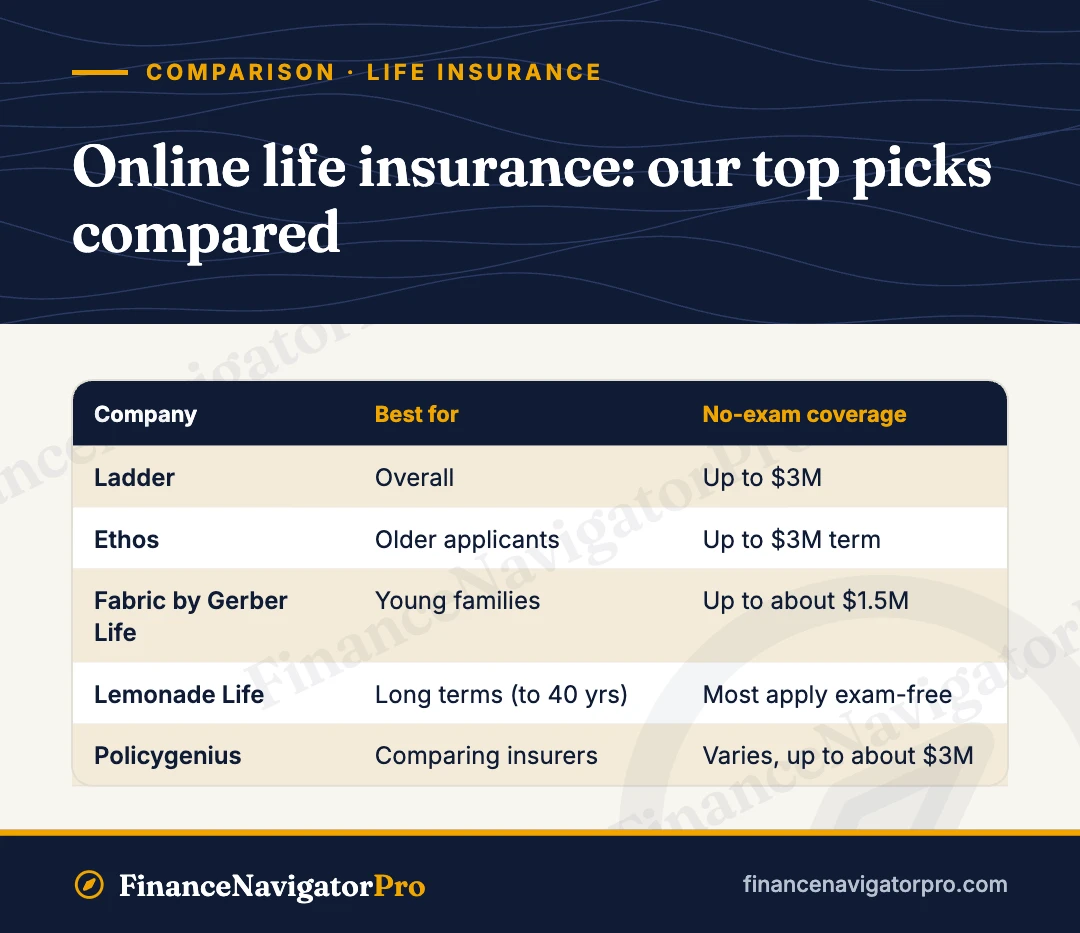
- Best overall: Ladder. Up to $3 million with no exam, and you can lower your coverage later as your needs shrink.
- Best for older applicants and policy choices: Ethos. Term life up to $3 million plus a guaranteed acceptance whole life option for ages 45 to 85.
- Best for young families: Fabric by Gerber Life. Policies issued by an A+ (Superior) rated insurer, with a free will included.
- Best for long terms: Lemonade Life. Term lengths up to 40 years and issue ages up to 75.
- Best for comparing insurers: Policygenius. A licensed broker that shows quotes from several insurers, including no-exam options.
Pricing and features checked November 2026; confirm on the provider’s site before signing up.
| Product | Best for | Issuing insurer (AM Best) | Max coverage | Terms | Ages (term) |
|---|---|---|---|---|---|
| Ladder | Overall | Amica Life (A+), S.USA Life (A-), Fidelity Security Life, by state | $3M no exam; more with health check | 10 to 30 years | About 20 to 60 |
| Ethos | Older applicants, choice | Several partners, A to A+ range | $3M term | 10 to 40 years | 18 to mid-60s |
| Fabric by Gerber Life | Young families | Western-Southern Life Assurance (A+) | $1.5M no exam; up to $5M | 10 to 30 years | 21 to 70 |
| Lemonade Life | Long terms | Banner Life (A) | High limits for qualifying applicants | 10 to 40 years | 20 to 75 |
| Policygenius | Comparing insurers | Varies by insurer you pick | Varies; no-exam up to about $3M | Varies | Varies |
What changed in online life insurance (2024 to 2026)
The online life insurance market has shuffled a lot in the last two years, and many older “best of” lists still recommend companies you can no longer buy from. Here is what we found when we checked each brand:
- Haven Life stopped accepting new applications on January 3, 2024. MassMutual services existing policies, but new customers cannot apply.
- Bestow moved to an enterprise software business and its consumer life insurance became Lantern Insurance Company, part of Sammons Financial Group. Lantern no longer sells new term policies and only services existing ones.
- Lemonade Life switched its insurance partner in 2024. Policies are now issued by Banner Life Insurance Company instead of North American Company.
- Banner Life (formerly part of Legal & General America) was acquired by Meiji Yasuda. In March 2026, AM Best lowered Banner Life’s financial strength rating from A+ (Superior) to A (Excellent), with a stable outlook. A is still a strong rating, but some websites have not updated it yet.
- Fabric rebranded as Fabric by Gerber Life and is part of Western & Southern Financial Group.
None of the five companies below has stopped selling to new US customers as of November 2026. If you are new to the product itself, start with our explainer on what term life insurance is and how it differs from permanent coverage.
1. Ladder — Best overall
Ladder sells term life insurance entirely online. You answer health and lifestyle questions, and most applicants can get up to $3 million of coverage without a medical exam. Coverage starts at $100,000. Larger amounts may require a free at-home health check, and NerdWallet’s 2026 review reports coverage up to $8 million in that case. Term lengths are 10, 15, 20, 25, or 30 years, and the oldest applicants (around age 60) are limited to a 10-year term.
The feature that sets Ladder apart is flexibility after you buy. You can lower your coverage amount as your mortgage shrinks or your kids grow up, and your premium drops to match. For example, cutting $1 million of coverage to $750,000 cuts the next premium by about a quarter. That makes it easy to “ladder” your protection down instead of overpaying for decades.
Policies are issued by one of several insurers depending on your state. Ladder’s site names Amica Life Insurance Company, rated A+ (Superior) by AM Best with a stable outlook as of March 2026; S.USA Life Insurance Company, rated A- (Excellent) as of November 2025; and Fidelity Security Life Insurance Company. Ask which insurer will issue your policy and check its current rating on AM Best before you sign.
Sample rate: Ladder advertises prices starting around $5 a month for a $100,000, 10-year policy for a 20-year-old in the Preferred Plus health class (rate valid as of April 2026). Your quote will depend on age, health, and other factors.
Pros
- Up to $3 million with no medical exam for qualifying applicants
- Coverage can be reduced later, with lower premiums
- Fully online application with an instant decision for many people
- Main issuing insurer (Amica Life) carries an A+ rating
Cons
- Term life only, no permanent policies
- No riders, including no accelerated death benefit rider
- Issuer depends on your state, and ratings differ among them
- Upper age limit around 60 is lower than some rivals
Price: Based on age, health, coverage, and term. Get a free online quote; no fees to apply.
Who it’s for: Healthy adults under 60 who want a large policy without an exam and want the option to scale coverage down over time.
2. Ethos — Best for older applicants and policy choices
Ethos is an online insurance agency that matches you with one of its partner insurers. You cannot choose the insurer yourself. Term coverage runs from $15,000 up to $3 million, with term lengths from 10 to 40 years. Most people answer health questions online without an exam, though Ethos may check records from MIB Group and occasionally asks for more information.
Where Ethos stands out is range. Besides term life, it offers a guaranteed acceptance whole life policy for ages 45 to 85 with no health questions, which is useful for people who cannot qualify for term coverage. Ethos says applicants 69 or younger can keep term coverage until age 80. It is not available in New York.
Ethos’s partner insurers include Banner Life, Protective Life, TruStage (CMFG Life and MEMBERS Life), Ameritas, and North American. Ethos lists Protective at A+ (Superior), and TruStage and Ameritas at A (Excellent). Banner Life is now rated A (Excellent) after AM Best’s March 2026 downgrade, even though some pages still show A+. Your application will show which company issues your policy.
Sample rates: NerdWallet’s 2026 review lists Ethos monthly rates of $22.59 for a 30-year-old man and $16.86 for a 30-year-old woman, for a 20-year, $500,000 term policy, nonsmoker in excellent health in the best (super preferred) health class. Treat these as illustrations, not quotes.
Pros
- Term coverage up to $3 million with no exam for many applicants
- Term lengths up to 40 years
- Guaranteed acceptance whole life for ages 45 to 85
- Low $15,000 minimum suits small, targeted needs
Cons
- You cannot choose your insurer
- Not available in New York
- Guaranteed acceptance whole life costs far more per dollar of coverage than term
- Ratings vary across the partner insurers
Price: Based on age, health, coverage, and term. Free online quote.
Who it’s for: Adults in their 50s and 60s, and anyone who wants term and simple whole life options in one place.
3. Fabric by Gerber Life — Best for young families
Fabric was built for parents, and it is now part of the Western & Southern Financial Group alongside Gerber Life. Policies are issued by Western-Southern Life Assurance Company, which AM Best affirmed at A+ (Superior) in April 2026 and moved to a positive outlook. That is the strongest issuer rating among our picks.
Typical coverage runs from $100,000 to $1.5 million without a medical exam. Fabric can go up to $5 million, but amounts above roughly $1.5 million may require an exam. Term lengths are 10, 15, 20, 25, or 30 years depending on age, and issue ages are 21 to 70. Fabric is not available in New York.
The extras are aimed at families: Fabric includes a free will you can use to name guardians for your children, premiums are locked for the life of the policy, and you can manage everything in a mobile app.
Pros
- Issuing insurer rated A+ (Superior) by AM Best
- Free will included, handy for naming guardians
- Issue ages up to 70
- Coverage up to $5 million for those who qualify
Cons
- No-exam coverage tops out around $1.5 million
- Not available in New York
- Maximum term is 30 years
- Available term lengths shrink as you get older
Price: Based on age, health, coverage, and term. Free online quote.
Who it’s for: Parents who want a top-rated insurer and a simple way to handle both life insurance and a basic will.
4. Lemonade Life — Best for long terms
Lemonade is better known for renters and pet insurance, but its life insurance agency sells term policies issued by Banner Life Insurance Company. Banner Life is rated A (Excellent) by AM Best after its March 2026 rating change. Lemonade Life is available in every state except New York.
Lemonade offers the widest set of term lengths here: 10, 15, 20, 25, 30, 35, or 40 years. Issue ages run from 20 to 75, subject to underwriting, and coverage starts at $100,000, with high limits for qualifying applicants. Most people can apply without a medical exam, although some may be asked for one. The application asks about your health and lifestyle.
A 40-year term can make sense if you are in your 20s or early 30s and want coverage to last until your youngest child is well into adulthood, or until a 30-year mortgage is paid off with room to spare.
Pros
- Term lengths up to 40 years
- Issue ages up to 75
- High coverage limits for qualifying applicants
- Simple online application from a well-known brand
Cons
- Banner Life’s rating dropped from A+ to A in 2026
- Lemonade does not publish a firm no-exam coverage cap
- Not available in New York
- Term life only, no permanent coverage
Price: Lemonade advertises policies “starting from $8/mo” but does not state the assumptions behind it. Get a personal quote.
Who it’s for: Younger buyers who want a long term, and older applicants up to 75 who still want term coverage.
5. Policygenius — Best for comparing insurers
Policygenius is not an insurer. It is a licensed independent insurance broker that lets you compare quotes from multiple companies in one place, with licensed agents available by phone. Quotes are free and non-binding, and the insurer you pick sets your final premium after underwriting.
That makes it the best choice if you want to see more than one company’s price. For no-exam coverage, Policygenius lists insurers such as Banner Life (roughly $100,000 to $2 million for ages 20 to 60), Pacific Life ($50,000 to $3 million for ages 18 to 70), Mutual of Omaha, Transamerica, and Protective. It also offers simplified issue and guaranteed issue products for people who cannot qualify for traditional term coverage.
Because Policygenius works with many insurers, the financial strength rating depends on the company you choose. Check each insurer’s AM Best rating on its quote before you apply.
Pros
- Compare several insurers at once
- No-exam options up to about $3 million with some insurers
- Licensed agents help with applications and tricky health histories
- Covers term, permanent, simplified issue, and guaranteed issue
Cons
- Expect follow-up phone calls and emails from agents
- The process can take longer than a single-company instant policy
- Insurer quality varies, so you need to check ratings yourself
- Coverage limits and ages depend on the insurer
Price: Free to compare quotes. Premiums depend on the insurer and your profile.
Who it’s for: Shoppers who want to compare prices side by side, and people with health conditions who benefit from an agent’s help.
How no-exam life insurance works
“No medical exam” does not mean “no questions.” There are three main types, and they differ a lot in price and coverage:
- Accelerated underwriting: You answer detailed health questions, and the insurer checks databases such as prescription history, MIB records, and driving records. Healthy applicants can get large policies, often up to $1 million to $3 million, at prices close to fully underwritten rates. Ladder, Ethos, Fabric, and Lemonade mostly work this way.
- Simplified issue: Fewer questions and smaller policies, usually priced higher. Learn more in our guide to simplified issue life insurance.
- Guaranteed issue: No health questions at all, but low coverage amounts, high premiums, and usually a waiting period before the full benefit pays. This is common for final expense insurance.
For a deeper look at who qualifies and the tradeoffs, read our full guide to no medical exam life insurance. A key point: answer every health question honestly. Misstatements on your application can give the insurer grounds to contest a claim during the first two years.
How to choose an online life insurance company
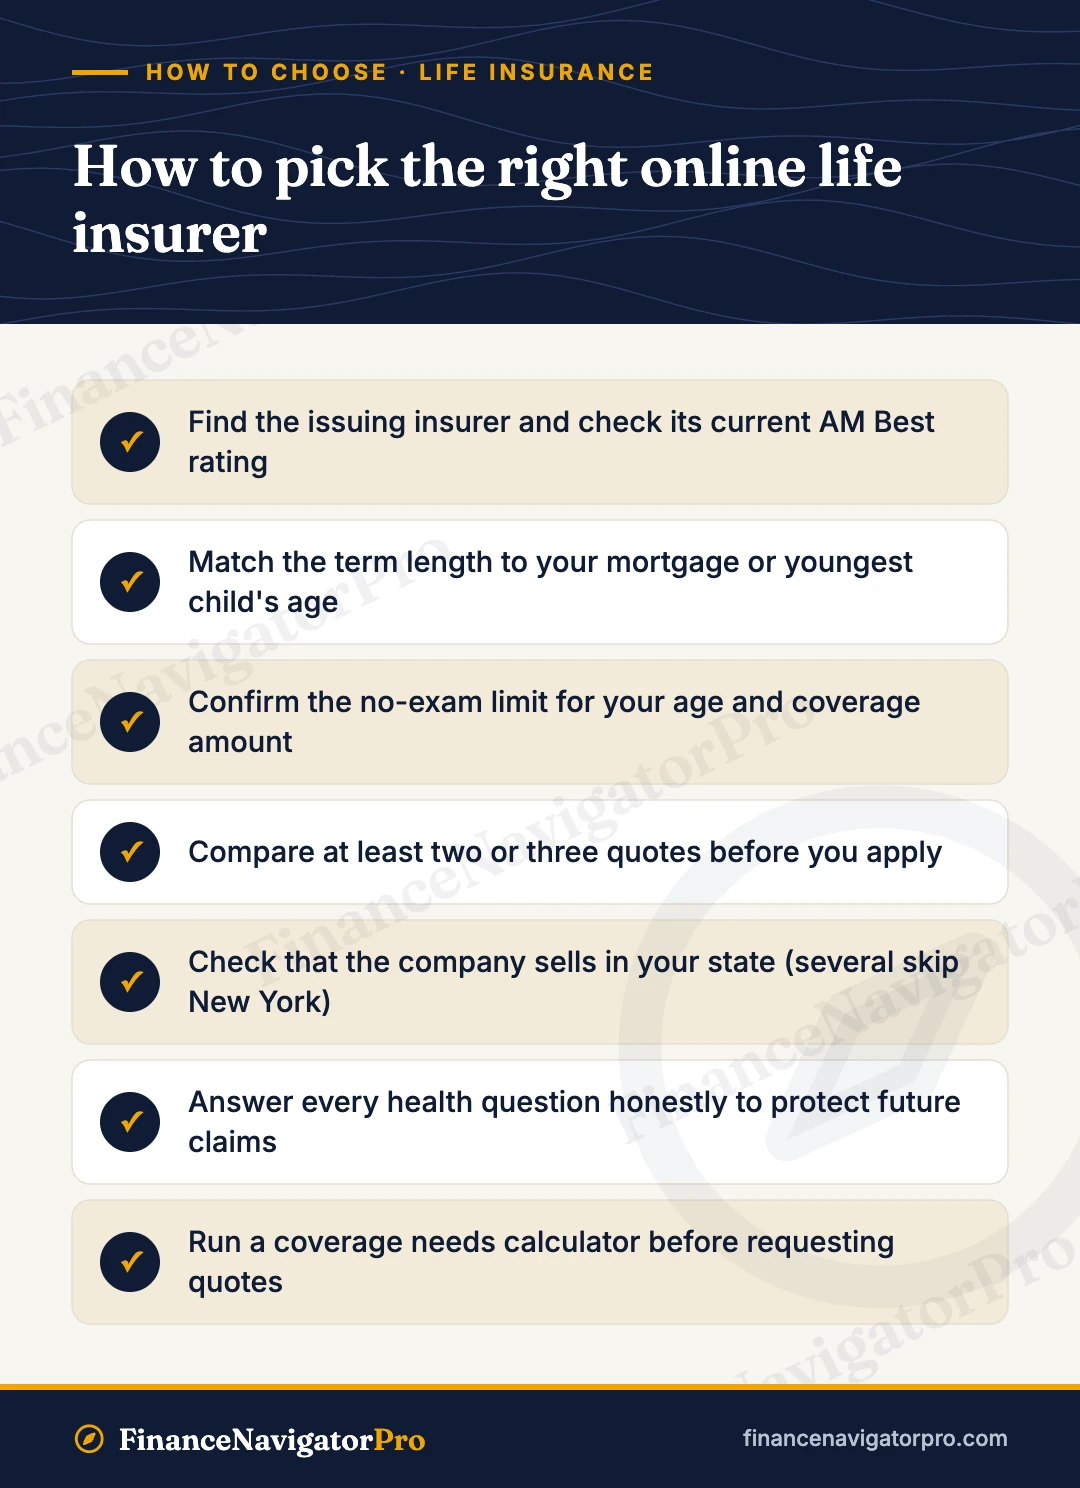
1. Check the issuing insurer’s financial strength
Many online brands are agencies, not insurers. The company that pays your claim is the issuing insurer named on your policy. Look for an AM Best rating of A- (Excellent) or better, and check the rating date, since ratings change.
2. Match the term to your longest obligation
Pick a term that lasts until your youngest child is independent, your mortgage is paid off, or you reach retirement with enough savings. If you are unsure whether you need term or permanent coverage, compare the two in our guide to the difference between term and whole life insurance.
3. Know the no-exam limit for your age
No-exam limits often shrink as you get older. If you need more than the no-exam cap, a short at-home exam can unlock more coverage and sometimes a better price.
4. Compare at least two or three quotes
Each insurer weighs health, age, and lifestyle differently. The same person can get noticeably different quotes from different companies, so it pays to compare.
5. Check state availability
Several of our picks do not sell in New York. New York residents should check Policygenius or ask an agent about insurers licensed in that state.
6. Look at flexibility and extras
Ladder lets you lower coverage later, Fabric includes a free will, and Ethos offers a whole life backup option. Decide which of these matters to you before you compare prices.
How we chose
We did not buy policies or run test applications. Instead, we compared online life insurance providers using their official websites, AM Best rating announcements, and 2026 reviews from established personal finance publishers. We first removed companies that no longer accept new customers, then compared the rest on these criteria:
- Whether new US customers can apply online in November 2026
- The issuing insurer and its current AM Best financial strength rating
- Maximum coverage and no-exam coverage limits
- Available term lengths and issue ages
- State availability, extras, and policy flexibility
You can read more about how we research and update content in our editorial policy.
Run your numbers first
Before you request quotes, figure out how much coverage you actually need. Buying too little leaves your family short, and buying too much wastes money every month for decades.
- Use our term life insurance needs calculator to total your income replacement, debts, and future costs like college.
- Estimate premiums for different terms and coverage amounts with the term life insurance calculator.
- Get a broader coverage estimate with the life insurance calculator.
- Check how much your family could draw on in savings with the emergency fund calculator.
Life insurance is one piece of a wider safety net. Our guide on what insurance coverage you need covers health, disability, and property insurance, and our tips on how to lower your insurance premium can help keep costs down.
Pro tip: Apply while you are young and healthy. Term premiums are locked in for the full term, so a policy bought at 30 usually costs much less every year than the same policy bought at 40, and a new health condition can raise your rate or limit your options.
Frequently asked questions
Can I really get life insurance online without a medical exam?
Yes. Ladder, Ethos, Fabric, and Lemonade let many healthy applicants buy term coverage based on health questions and database checks. Ladder and Ethos offer up to $3 million without an exam for those who qualify. You may still be asked for an exam if your answers or records raise questions.
Is no-exam life insurance more expensive?
Not always. Accelerated underwriting policies for healthy applicants are often priced close to traditional policies. Simplified issue and guaranteed issue policies, which ask fewer or no health questions, generally cost more per dollar of coverage.
Can I still buy from Haven Life or Bestow?
No. Haven Life stopped accepting applications in January 2024, and MassMutual services existing policies. Bestow’s consumer insurer became Lantern, which no longer sells new term policies and only services existing ones.
Who actually pays the claim when I buy online?
The issuing insurer named on your policy pays the death benefit, not the website you bought through. For example, Fabric policies are issued by Western-Southern Life Assurance Company and Lemonade Life policies by Banner Life Insurance Company. Check that insurer’s AM Best rating.
How much life insurance do I need?
A common starting point is enough to replace several years of income plus your mortgage, other debts, and future costs like childcare and college, minus savings you already have. Our term life insurance needs calculator walks you through the math.
Can I cancel an online life insurance policy?
Yes. You can stop paying premiums on a term policy at any time, and coverage ends. Most states also require a free-look period after purchase during which you can cancel for a refund. Check your policy documents for the exact length in your state.
Bottom line
For most healthy adults under 60, Ladder is the best place to start thanks to up to $3 million of no-exam coverage and the ability to reduce it later. Ethos is a strong fit for older buyers who want a whole life fallback, Fabric by Gerber Life pairs an A+ rated insurer with a free will for parents, Lemonade Life offers the longest terms, and Policygenius is the easiest way to compare several insurers at once. Whichever you choose, confirm the issuing insurer’s rating, get at least two quotes, and buy the coverage your calculator says you need.
Keep reading