On this page
A low credit score makes borrowing harder and more expensive, but it does not shut you out. Several reputable online lenders consider borrowers with scores in the 500s and low 600s, and some look beyond your score entirely. Here are five lenders worth comparing, what to expect on rates and how to avoid predatory loans.
Disclosure: Some links may earn us a commission at no cost to you. It never affects our rankings. See our affiliate disclaimer.
Our top picks at a glance
- Best for thin or no credit: Upstart — considers education and job history alongside your score.
- Best for rate discounts: Upgrade — autopay and direct-pay discounts on loans up to $50,000.
- Best for fair credit: Avant — accepts scores in the mid-500s with next-day funding.
- Best for no minimum score: OneMain Financial — in-person branches and a secured loan option.
- Best for secured loans: Best Egg — can use your home fixtures as collateral to improve your rate.
Rates on bad credit loans are high: borrowers with scores below 580 who got loans through Credible paid an average APR near 30% over the past year. Lender terms change often. Pricing and features checked November 2026; confirm on each lender’s site before applying.
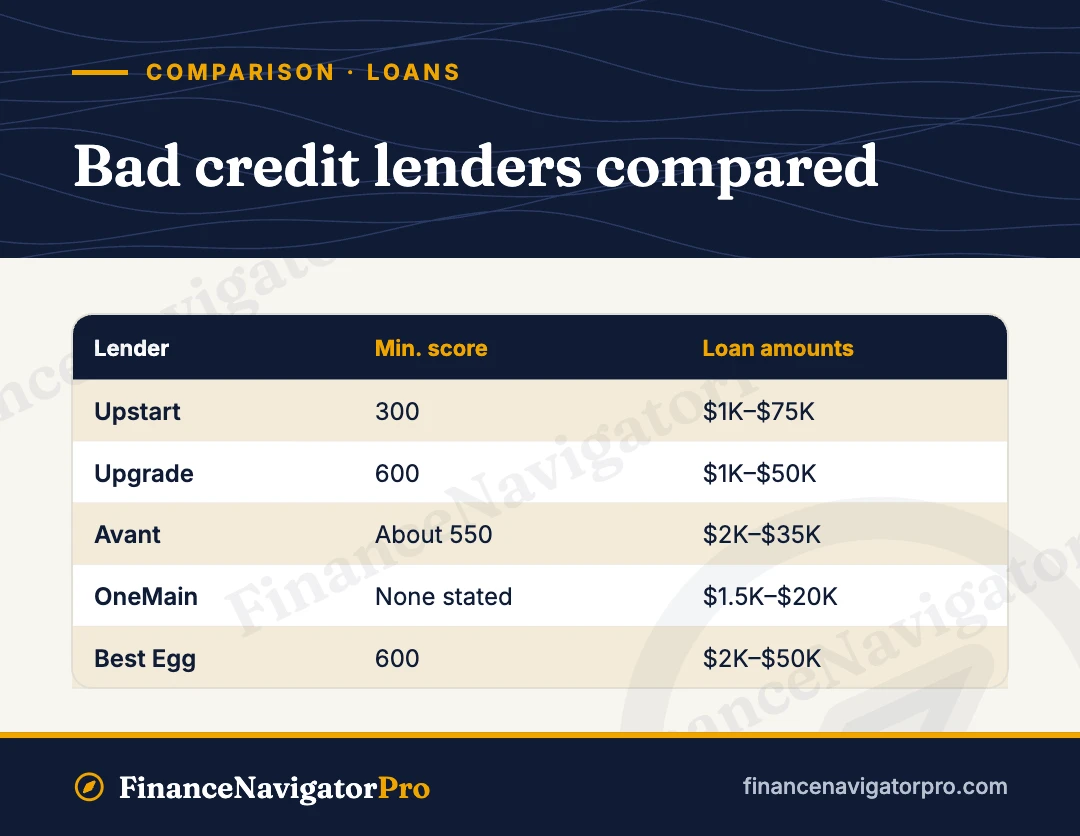
| Lender | Best for | Minimum credit score | Loan amounts |
|---|---|---|---|
| Upstart | Thin or no credit | 300 | $1,000–$75,000 |
| Upgrade | Rate discounts | 600 | $1,000–$50,000 |
| Avant | Fair credit | About 550 | $2,000–$35,000 |
| OneMain Financial | No minimum score | None stated | $1,500–$20,000 |
| Best Egg | Secured loans | 600 | $2,000–$50,000 |
1. Upstart — Best for thin or no credit
Upstart uses a lending model that weighs factors such as education and employment alongside your credit report. It accepts scores as low as 300, and can work for people with little or no credit history.
Pros
- Considers more than your credit score
- Loans up to $75,000
- Fast funding, often the next business day
Cons
- Origination fee can be high
- Only two repayment terms, three or five years
APR: up to 35.99%.
Who it’s for: young borrowers or anyone with a thin credit file and steady income.
2. Upgrade — Best for rate discounts
Upgrade lends to borrowers with scores from 600 and offers discounts for autopay and for having funds sent directly to your creditors when consolidating debt. It also allows joint applications.
Pros
- Rate discounts for autopay and direct creditor payment
- Co-borrower option can help you qualify
- Terms up to seven years
Cons
- Origination fee on all loans
- Requires a score of at least 600
APR: up to 35.99%.
Who it’s for: borrowers in the low 600s consolidating credit card debt.
3. Avant — Best for fair credit
Avant has focused on borrowers with fair credit for more than a decade. It accepts scores starting around the mid-500s, lets you prequalify with a soft credit check and usually funds the next business day.
Pros
- Accepts lower scores than many online lenders
- Soft-check prequalification
- Next-day funding in many cases
Cons
- Administration fee
- Maximum loan of $35,000
APR: up to 35.99%.
Who it’s for: fair-credit borrowers who need funds quickly.
4. OneMain Financial — Best for no minimum score
OneMain does not publish a minimum credit score and offers both unsecured loans and secured loans backed by a vehicle. It has hundreds of branches, so you can work with a loan specialist in person, and same-day funding is possible after approval.
Pros
- No stated minimum credit score
- Secured option can improve approval odds
- In-person branches and fast funding
Cons
- Rates tend to start higher than other lenders
- Origination fees vary by state
- Maximum loan of $20,000
APR: up to 35.99%.
Who it’s for: borrowers with poor credit who have a car to use as collateral or prefer in-person help.
5. Best Egg — Best for secured loans
Best Egg lends to borrowers with scores from 600 and offers secured loan options, including one that uses your home’s permanent fixtures as collateral. A secured loan can mean a lower rate or a larger amount than you would qualify for otherwise.
Pros
- Secured options can lower your rate
- Loans up to $50,000
- Fast funding after approval
Cons
- Origination fee
- Requires a score of at least 600
APR: up to 35.99%.
Who it’s for: homeowners rebuilding credit who want a lower rate.
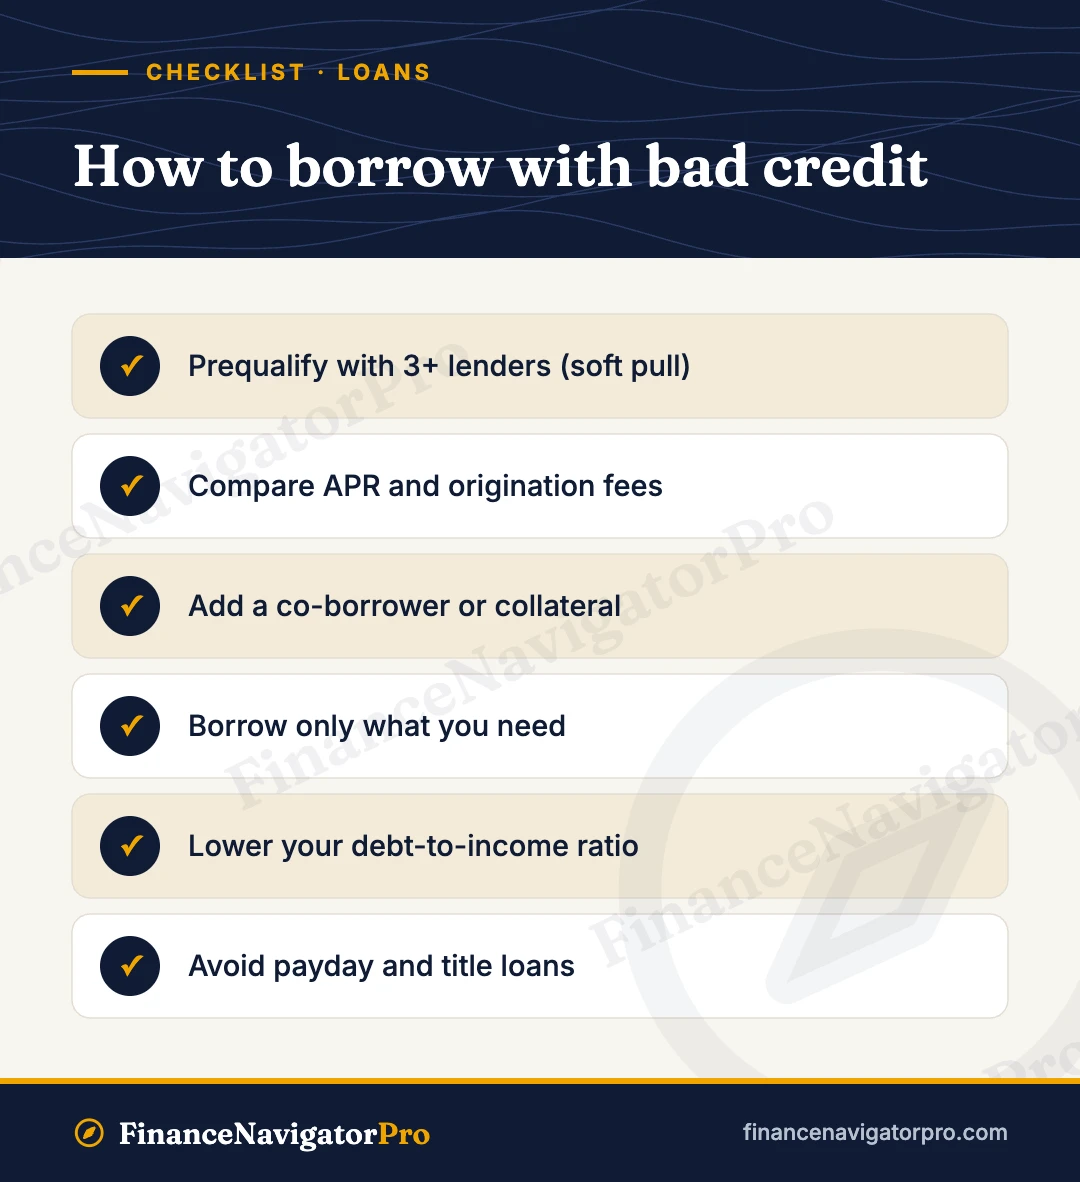
How to get a personal loan with bad credit
Prequalify with several lenders
Most online lenders let you check your rate with a soft credit pull that does not affect your score. Compare at least three offers on APR, fees and monthly payment.
Add a co-borrower or collateral
A creditworthy co-borrower or a secured loan can improve your approval odds and lower your rate.
Borrow only what you need
A smaller loan means less interest and a payment you can manage. Check affordability with the personal loan calculator.
Lower your debt-to-income ratio
Lenders weigh your debt-to-income ratio heavily. Calculate yours with the debt-to-income calculator.
Avoid predatory loans
Steer clear of payday loans, title loans and lenders that guarantee approval or charge APRs in the triple digits. Read more in quick loans for emergency cash.
How we chose
We compared national lenders that publish requirements for borrowers with fair or poor credit, using lender information and reputable November 2026 reviews. We did not accept payment for placement.
- Minimum credit score and alternative underwriting
- Maximum APR and fees
- Loan amounts and terms
- Co-borrower and secured loan options
- Funding speed
Frequently asked questions
What credit score do I need for a personal loan?
Many lenders require 600 or higher, but some accept scores in the 500s, and a few, like Upstart and OneMain, consider applicants with lower or limited credit.
Will applying hurt my credit?
Prequalifying uses a soft pull and does not affect your score. A formal application usually triggers a hard inquiry, which may lower your score by a few points temporarily.
Can a personal loan help rebuild credit?
Yes, if you make every payment on time. Lenders report to the credit bureaus, and using a loan to pay off cards can also lower your credit utilization. See how to raise your credit score fast.
Is a bad credit loan worth it?
It can be if it replaces higher-cost debt or covers a true emergency. Compare the total cost with alternatives such as a credit union loan, a secured card or a debt payoff plan.
Bottom line
Upstart is a strong choice for thin credit, Upgrade for rate discounts, Avant for fair credit, OneMain if you have no minimum score to meet and Best Egg for a secured loan. Prequalify with several lenders, compare APRs and fees, and borrow only what you can repay. Prefer a general list? See the best personal loans. This article is educational and not personal financial advice.
Keep reading