On this page
A home equity line of credit (HELOC) lets you borrow against your home’s value as you need it, often at a lower rate than credit cards or personal loans. With first-mortgage rates around 7%, a HELOC is also a way to tap equity without refinancing a low-rate mortgage. Here are five strong HELOC lenders and how to compare offers.
Disclosure: Some links may earn us a commission at no cost to you. It never affects our rankings. See our affiliate disclaimer.
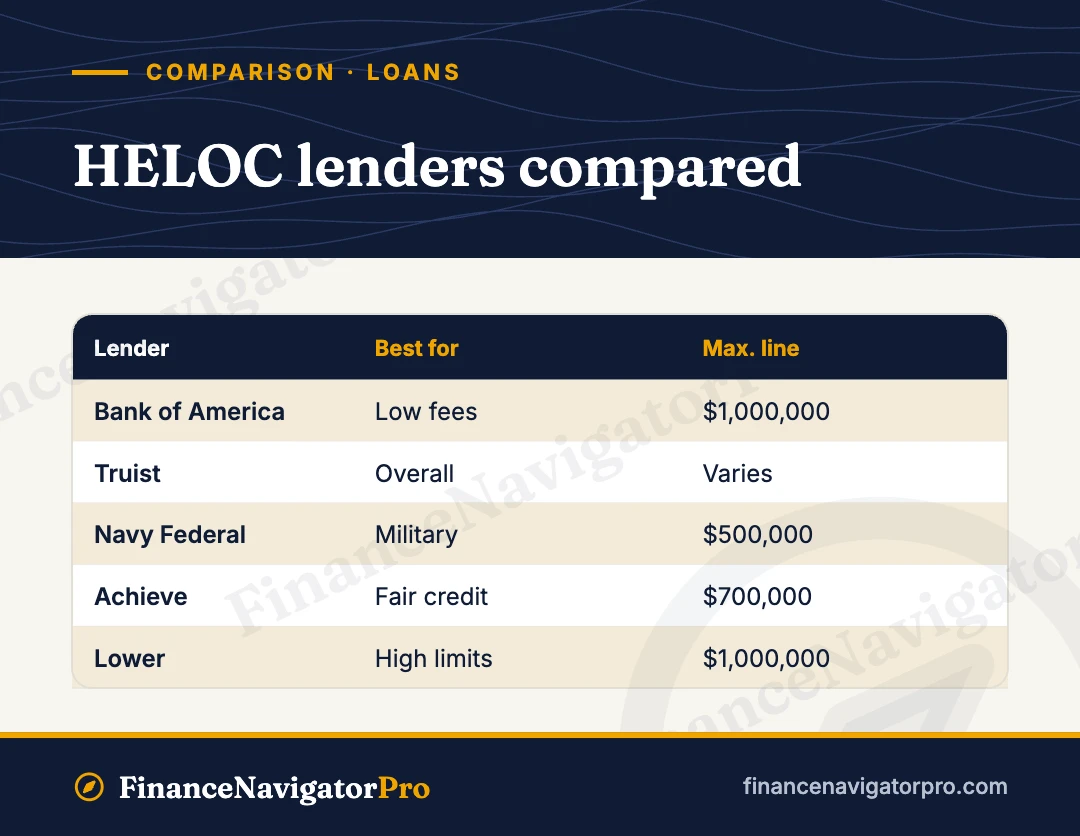
Our top picks at a glance
- Best for low fees: Bank of America — no application fee, no annual fee and no closing costs on lines up to $1 million.
- Best overall: Truist — a well-rated bank HELOC with a fixed-rate option.
- Best for military members: Navy Federal Credit Union — borrow up to 95% of your home’s value.
- Best for fair credit: Achieve — accepts scores from 600 with a fixed rate.
- Best for high limits: Lower — lines up to $1 million and 90% combined loan-to-value.
The average HELOC rate was 7.49% as of November 11, 2026, according to Bankrate’s survey of large lenders. Your rate depends on your credit, equity and location. Pricing and features checked November 2026; confirm details with each lender before you apply.
| Lender | Best for | Max. combined LTV | Max. line |
|---|---|---|---|
| Bank of America | Low fees | Varies | $1,000,000 |
| Truist | Overall | Varies | Varies |
| Navy Federal | Military members | 95% | $500,000 |
| Achieve | Fair credit | 85% | $700,000 |
| Lower | High limits | 90% | $1,000,000 |
1. Bank of America — Best for low fees
Bank of America advertises no application fee, no annual fee and no closing costs on HELOCs up to $1 million, which keeps the upfront cost low. Existing customers may qualify for rate discounts.
Pros
- No application, annual or closing fees on eligible lines
- Relationship and autopay discounts
- Large branch network
Cons
- Rates are not always the lowest
- Some fees may apply if you close the line early
Who it’s for: borrowers who want to minimize upfront costs.
2. Truist — Best overall
Truist, a large regional bank, earns strong marks for its HELOC and lets borrowers lock part of their balance at a fixed rate for more predictable payments. It is available in its regional footprint, mainly in the Southeast and Mid-Atlantic.
Pros
- Option to lock a fixed rate on part of the balance
- Possible discounts for existing customers
- In-person support at branches
Cons
- Not available nationwide
- Closing can take longer than online lenders
Who it’s for: homeowners in Truist’s area who want a bank relationship.
3. Navy Federal Credit Union — Best for military members
Navy Federal lets eligible members borrow up to 95% of their home’s value, minus their mortgage balance, with lines up to $500,000. Membership is open to service members, veterans, Department of Defense personnel and their families.
Pros
- Up to 95% combined loan-to-value
- Lines up to $500,000
- Strong member service
Cons
- Membership required
- Minimum credit score not disclosed
Who it’s for: eligible military members who want to borrow more of their equity.
4. Achieve — Best for fair credit
Achieve offers a HELOC with a fixed rate, credit lines from $15,000 to $700,000 and a minimum credit score of 600. You can choose repayment terms of 10, 15, 20 or 30 years, and it does not charge a prepayment penalty.
Pros
- Accepts credit scores from 600
- Fixed rate for predictable payments
- No prepayment penalty
Cons
- Shorter draw period than many lenders
- Maximum 85% combined loan-to-value
Who it’s for: borrowers with fair credit who want a fixed payment.
5. Lower — Best for high limits
Lower offers HELOCs up to $1 million and lets you borrow up to 90% of your home’s value combined with your mortgage. It has a fixed-rate option and accepts credit scores from 600.
Pros
- Lines up to $1 million
- Up to 90% combined loan-to-value
- Fixed-rate option
Cons
- Charges an annual fee
- Slower closing than some lenders
Who it’s for: homeowners with significant equity who need a large line.
How to choose a HELOC lender
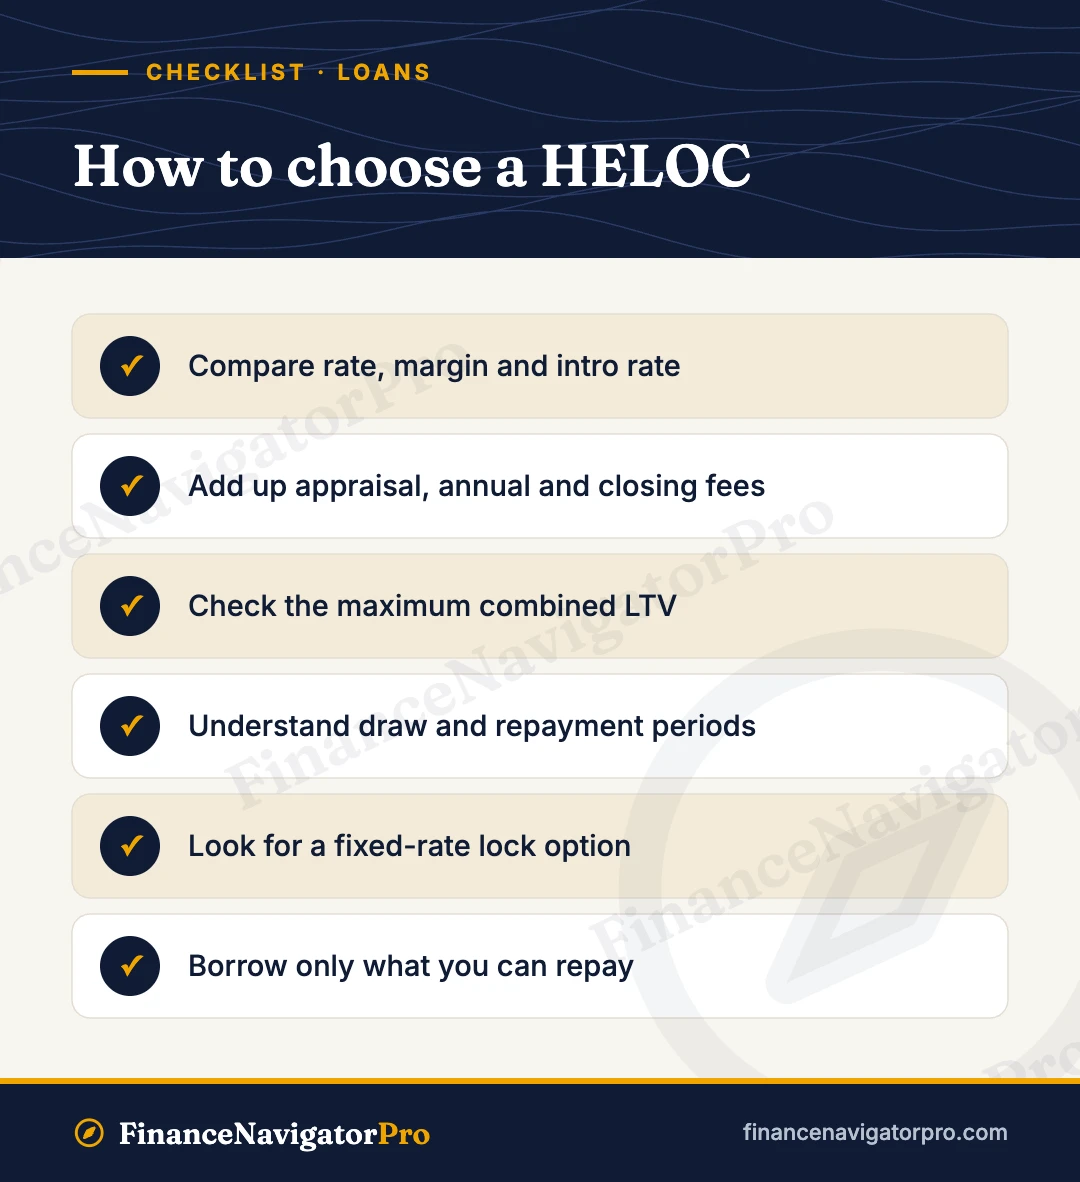
Compare the full cost
Look at the starting rate, the margin over the prime rate, any introductory rate, and fees such as appraisal, origination, annual and early closure fees.
Check how much you can borrow
Most lenders cap your combined loan-to-value (CLTV) at 80% to 90%. Estimate your available equity with the home equity calculator.
Understand the draw and repayment periods
Most HELOCs have a draw period of up to 10 years, often with interest-only payments, followed by a repayment period when payments rise. Plan for the higher payment.
Consider a fixed-rate option
Because HELOC rates are variable, a fixed-rate lock can protect you if rates rise.
HELOC or home equity loan?
A home equity loan gives you a lump sum at a fixed rate. Compare both in HELOC vs. home equity loan.
How we chose
We compared national and large regional HELOC lenders using lender information and reputable November 2026 reviews. We did not accept payment for placement.
- Fees and closing costs
- Maximum combined loan-to-value and line amount
- Credit score requirements
- Fixed-rate options and repayment flexibility
- Availability and customer experience
Run your numbers
- Estimate payments with the HELOC calculator.
- Compare with the home equity loan calculator.
- Consider a cash-out refinance only if it beats your current mortgage rate.
Frequently asked questions
What credit score do I need for a HELOC?
Many lenders require at least 620 to 680, though some, like Achieve and Lower, accept 600. Higher scores usually earn lower rates.
Is HELOC interest tax-deductible?
Interest may be deductible if you use the money to buy, build or substantially improve the home that secures the loan and you itemize deductions.
Can I lose my home with a HELOC?
Yes. Your home secures the line, so missing payments can lead to foreclosure. Borrow only what you can repay.
Should I use a HELOC to pay off credit cards?
It can lower your rate, but it turns unsecured debt into debt secured by your home. Make sure you will not run the cards back up. See how to pay off credit card debt.
Bottom line
Bank of America is a strong choice for low fees, Truist for an all-around bank HELOC, Navy Federal for military members, Achieve for fair credit and Lower for high limits. Get quotes from at least three lenders and compare the full cost before you borrow. This article is educational and not personal financial advice.
Keep reading